Even the healthiest seed will struggle if planted in the wrong soil. Investments can work in a similar way, since some assets benefit from being held in specific types of accounts, especially when it comes to how they are taxed. This idea is known as “asset location.” It does not refer to where assets are held geographically. Instead, it is the practice of placing each investment in the account type where it can grow most efficiently. This might include a taxable brokerage account, a tax-deferred account like a traditional IRA or 401(k), or a tax-free account like a Roth IRA.
Most investors spend a great deal of time thinking about what to invest in. However, where those investments are held can matter just as much. Asset location is different from asset allocation, which is how investors spread their money across different types of investments like stocks and bonds. The main goal of asset location is to maximize the amount you keep after taxes, since that is what actually matters for your financial planning needs. Ultimately, asset location aims to improve the likelihood that you will reach your financial goals over your lifetime. What key factors should investors keep in mind today?
Matching the right investment with the right account type
There are two important ideas to understand when it comes to asset location. The first is that investment accounts generally fall into two categories: taxable and tax-advantaged. Taxable accounts are those where gains are subject to taxes, such as ordinary income rates or capital gains rates, depending on the situation. Tax-advantaged accounts, on the other hand, help protect gains from taxes, but they come in many forms and each has its own specific rules.
The second key idea is that investments differ in how “tax-efficient” they are. An investment is considered tax-inefficient when a portion of its return is lost to taxes each year. This often happens because the investment produces income that is taxed at ordinary income rates, such as interest from corporate bonds, or because it frequently distributes short-term capital gains, as some funds do.
The goal of asset location is to hold tax-inefficient investments in accounts where their income is sheltered from taxes, while using taxable accounts for investments that are more tax-friendly, including those that will likely be held for a long time or that already receive relatively favorable tax treatment.
While this concept sounds straightforward, it takes careful planning in practice. This is because there are often limits on how much can be contributed to tax-advantaged accounts, along with rules about when funds can be taken out.
Different account types offer a range of opportunities
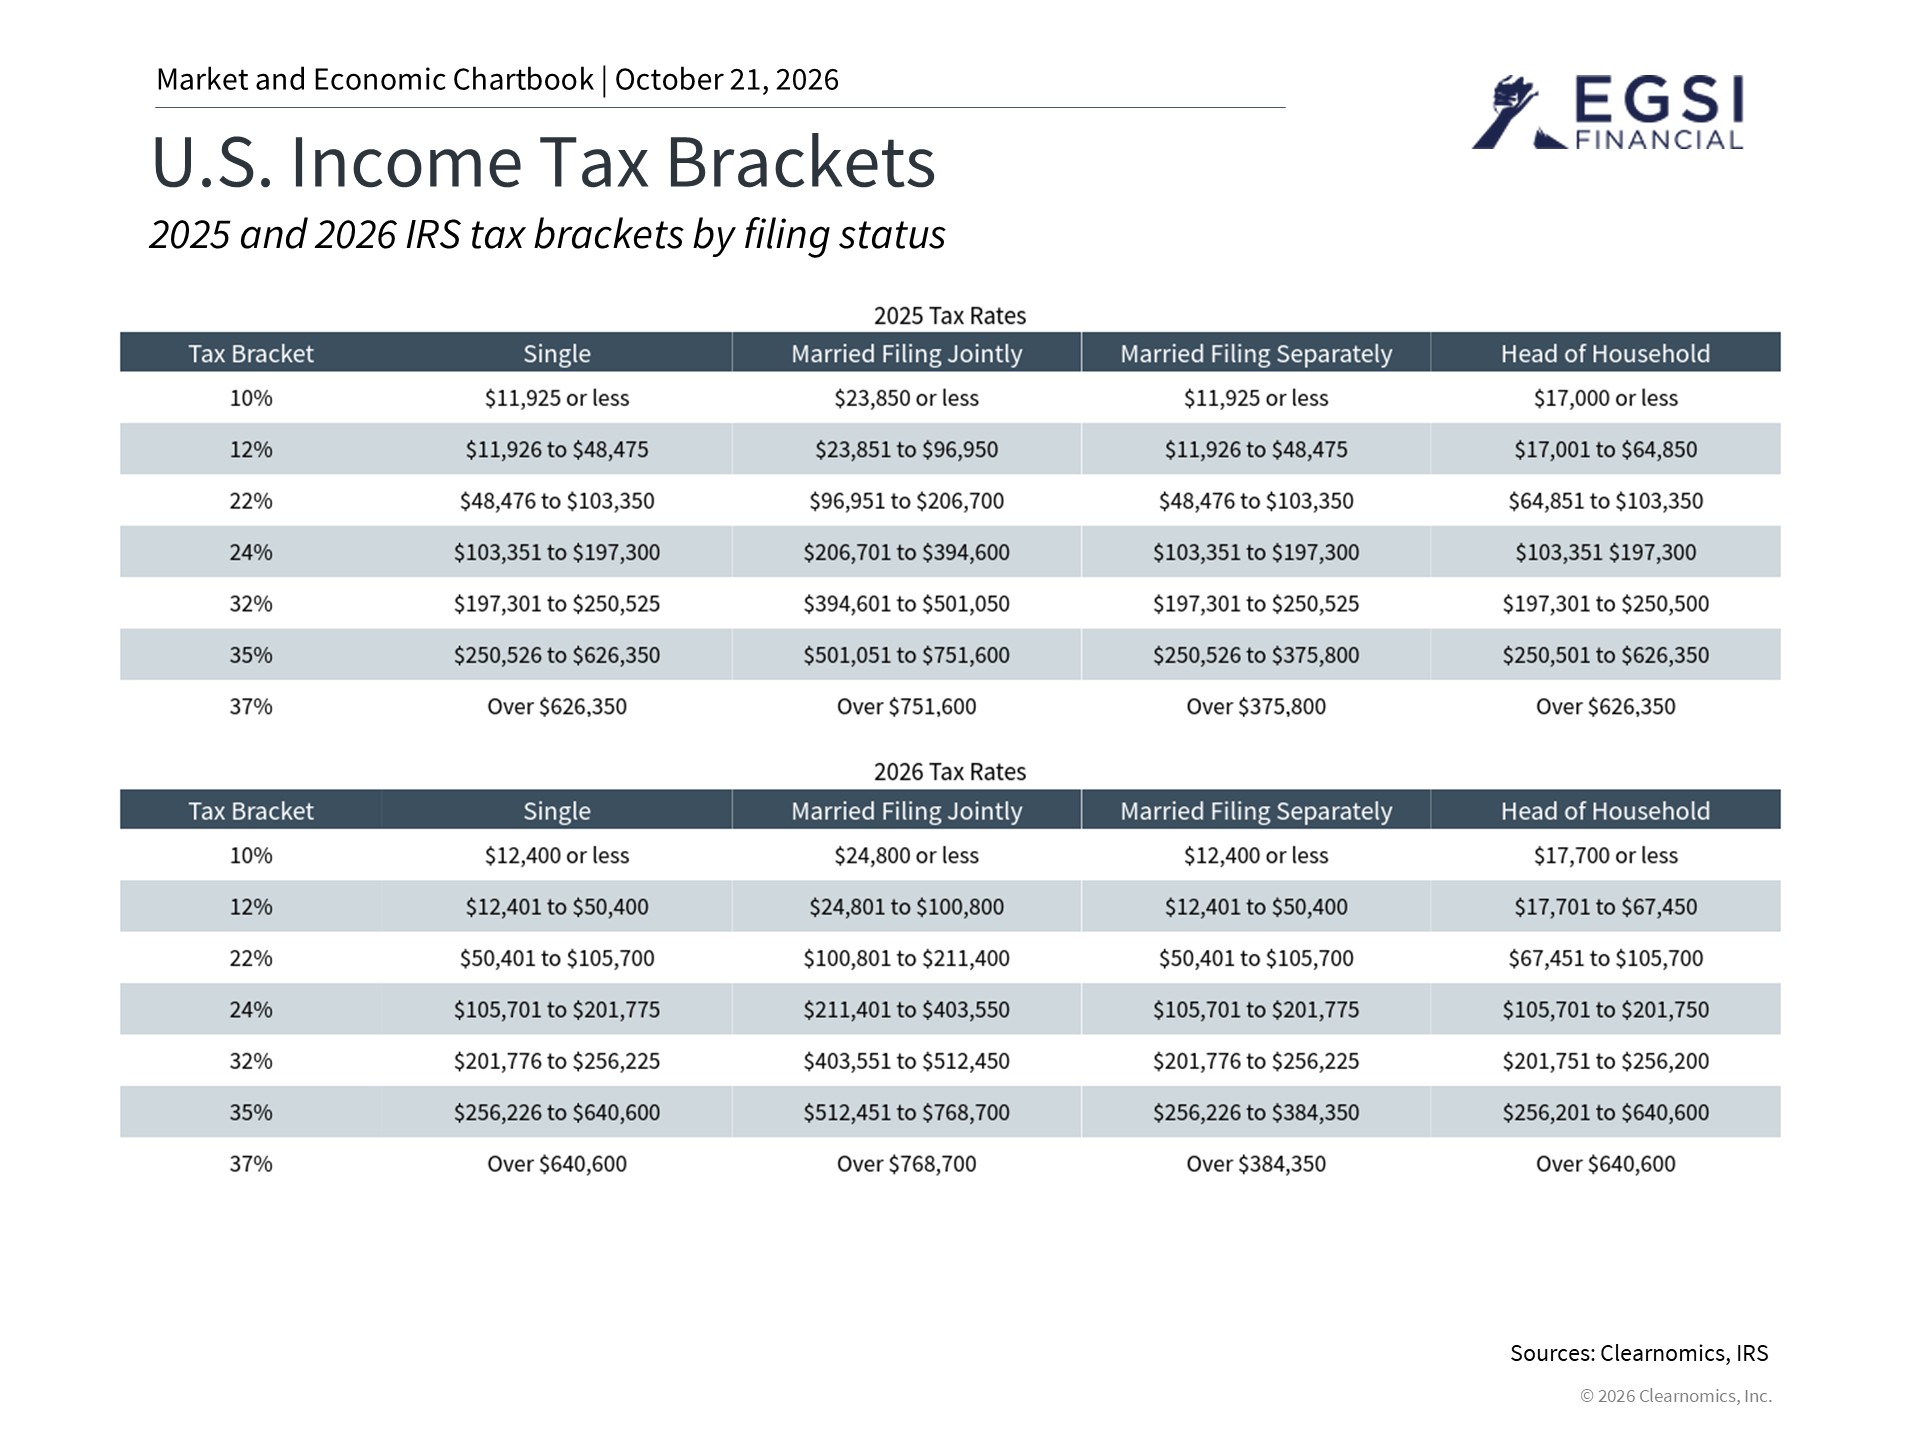
Taxable accounts, such as traditional brokerage accounts, are flexible and easy to access. They have no age restrictions on withdrawals, no contribution limits, and no early withdrawal penalties. The main drawback is that these accounts are subject to current taxation on dividends, interest, and realized capital gains. Interest and short-term gains are taxed at ordinary income rates, while qualified dividends and long-term capital gains are taxed at lower, preferential rates.1 The accompanying chart shows the federal income tax rates and brackets for 2026, which peak at 37%, while long-term capital gains tax peaks at 20%.2
Given this, taxable accounts are generally well-suited for tax-efficient or tax-exempt investments. Examples include low-dividend stocks held for the long term and exchange traded funds (ETFs) with low turnover. ETFs are funds that trade on a stock exchange and hold a collection of assets. Municipal bonds are another example, since their interest is generally exempt from federal, and in some cases state, income tax. Even though these accounts do not come with built-in tax benefits, certain strategies such as tax loss harvesting or charitable gifting can help manage annual taxes.
Tax-advantaged accounts include vehicles such as Roth IRAs and employer-sponsored 401(k) plans, among others. With a Roth IRA, contributions are made with after-tax dollars, meaning they are not tax-deductible. However, earnings can grow tax-free, and qualified withdrawals are also not taxable. This makes Roth accounts particularly attractive for assets with higher expected growth, since most of the potential gains can build up over time without creating a future tax bill.
Traditional IRAs work differently. They allow pre-tax contributions, meaning you get a tax deduction upfront, but withdrawals are taxed at ordinary income rates. Since all earnings are reinvested without being taxed along the way, the total balance can grow faster than in a standard taxable account. These accounts are well-suited for income-heavy or tax-inefficient assets that would otherwise generate annual taxable income. Examples include high-yield fixed income securities, high-dividend stocks, and Real Estate Investment Trusts (REITs), which are companies that own income-producing real estate.
Planning considerations for long-term strategies
Investors should start by thinking about their personal needs, including liquidity (the ability to access cash quickly), major expenses, education funding, retirement income, and time horizon. This helps determine the right mix of accounts to use. It also means weighing the advantages and disadvantages of placing funds in specific types of accounts.
One important consideration is balancing long-term investing with short-term liquidity needs. Locking money away for a longer period can offer tax benefits, but it also means losing access to those funds when needed. A Roth IRA, for instance, can serve as a liquidity option because original contributions can be withdrawn tax-free and penalty-free at any time.3
For estate planning purposes, there are additional factors to keep in mind. Taxable brokerage accounts are traditionally seen as short-term liquidity pools and can be effective tools for passing on wealth. When assets in these accounts are transferred at death, heirs receive what is called a “step-up in basis,” which means the value of the asset is reset to its current market price. This helps heirs avoid larger capital gains taxes and preserve more of the wealth being transferred.4
Investors can also match assets to specific financial goals using Health Savings Accounts (HSAs) and education savings accounts. HSAs offer a unique triple-tax advantage, meaning contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are also tax-free. This makes an HSA an excellent vehicle for long-term growth if you are able to pay current medical bills out of pocket and let the balance build over time. For education funding, investors can use 529 plans to grow assets tax-free.
Tax laws can change in the future, which may affect asset location strategies. Investors should also be aware that this approach requires additional effort to monitor and adjust over time.
Finally, taxes are only one piece of the financial planning puzzle. Asset location should support broader financial goals, not just minimize taxes in the current year. For retirees, this can mean arranging assets to support tax-efficient withdrawals, such as drawing from taxable accounts first to preserve tax-free growth. For those still building wealth, it can mean boosting after-tax compounding and turning incremental savings into greater value over a lifetime.
Rather than looking at each account in isolation, investors can get the most out of their tax advantages by treating all accounts as an interconnected system. When it comes to investing and retirement planning, asset location plays an important role in your overall strategy. While many investors focus on choosing the right assets, deciding where to hold those assets is equally important.
The bottom line? Asset location can support financial goals, bridging investment strategy and tax planning. By aligning the right account structures with the right asset types, and viewing these choices through the lens of broader financial planning, investors can potentially enhance after-tax returns without changing their overall investment mix.
References
1. https://www.irs.gov/taxtopics/tc409
2. https://www.irs.gov/filing/federal-income-tax-rates-and-brackets
3. https://www.irs.gov/publications/p590b
4. https://www.irs.gov/publications/p559
We are an independent financial services firm helping individuals create retirement strategies using a variety of investment and insurance products to custom suit their needs and objectives.
Advisory services offered through EGSI Investment Management, Inc., a Registered Investment Advisor with the State of Ohio. Insurance services offered through EGSI Financial, Inc.
Investing involves risk, including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. None of the information contained on this website shall constitute an offer to sell or solicit any offer to buy a security or any insurance product.
Any references to protection benefits, safety, security, or steady and lifetime income streams on this website refer only to fixed insurance products. They do not refer, in any way, to securities or investment advisory products. Annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Annuities are insurance products that may be subject to fees, surrender charges and holding periods which vary by insurance company. Annuities are not FDIC insured.
The information and opinions contained in any of the material requested from this website are provided by third parties and have been obtained from sources believed to be reliable, but accuracy and completeness cannot be guaranteed. They are given for informational purposes only and are not a solicitation to buy or sell any of the products mentioned. The information is not intended to be used as the sole basis for financial decisions, nor should it be construed as advice designed to meet the particular needs of an individual’s situation.